For contractors and trade businesses in Wilson, Rutherford and Davidson counties
Business Insurance for Contractors in Mt. Juliet and Middle Tennessee
Hi, I’m Dustin Rodgers. Plumbers, electricians, HVAC techs and lawn crews keep Middle Tennessee running, and a lot of them are my neighbors. I’d like to help you understand your coverage in plain language and protect the business you’ve worked hard to build. Call us, or request a quote below.

A local office for local trades
Call, stop by Providence Pkwy, or request a quote online.
The short answer
What insurance does a contractor in Tennessee need?
Most contractors in Tennessee look at general liability, workers’ compensation, commercial auto, and tools and equipment coverage, plus any bonds a license, permit or contract calls for. Tennessee construction employers with even one employee generally must carry workers’ comp. The right mix depends on your trade, your crew and your contracts.
You don’t need to know the insurance terms before you call. Tell us what you do, who you work for and what your contracts ask for, and we’ll explain your options in plain language. No jargon and no pressure.
Coverage, in plain language
What coverage can we help your business with?
We can help you look at general liability, workers’ comp, commercial auto, tools and equipment (inland marine), contractor and license bonds, commercial umbrella, and pollution coverage where it fits your work. Which coverages are available depends on carrier eligibility and underwriting, and every policy has its own limits, exclusions and terms. We’ll go over what applies to your business before you decide anything.
-
General liability
Can help pay for claims that your work injured someone or damaged their property, like a customer’s floor damaged during a job. Many general contractors, property managers and the state licensing board ask for proof of it. It generally doesn’t cover your own tools, your employees’ injuries or your vehicles.
-
Workers’ compensation
Can help pay medical bills and part of lost wages if an employee is hurt on the job. In Tennessee, construction employers with one or more employees generally must carry it, and most other businesses need it at five or more.
-
Commercial auto
For the trucks, vans and trailers that carry your crew, tools and materials around Middle Tennessee. Personal auto policies often limit coverage for vehicles used mainly for business, so let’s make sure yours are set up the right way.
-
Tools and equipment (inland marine)
Can help protect tools and equipment that travel from job to job, like drain cameras, testers, recovery machines and mowers, against covered theft or damage. General liability doesn’t cover your own gear.
-
Contractor and license bonds
License, permit and contract bonds that some licensing boards, cities, counties and project owners require. A bond protects the party who asked for it, not you, so we’ll explain how it works before you sign.
-
Commercial umbrella
Extra liability limits above your general liability, auto and employer’s liability, for when a contract or a bigger job asks for higher limits.
-
Pollution coverage, where it fits
Many general liability policies limit or exclude pollution claims. For work like sewer lines, refrigerants, mold or spraying chemicals, ask whether contractors pollution liability is available for your business.
Which coverages are available depends on carrier eligibility and underwriting, and every policy has its own limits, exclusions and terms. We’ll go over what applies to your business before you decide anything.
Insurance by trade
Find coverage for your trade
Every trade has its own risks, licensing rules and contract requirements. Pick yours for a closer look, or call us if you don’t see it here.
-
Plumbers insurance
Water damage, sewer and drain work, work vans and tools, Tennessee plumbing licenses, and permit bonds.
See plumbers coverage → -
Electricians insurance
Fire and completed work, shock and fall injuries, work trucks, Tennessee electrical licenses, and permit bonds.
See electricians coverage → -
HVAC contractors insurance
Installation errors, refrigerant and carbon monoxide questions, service vans, equipment waiting to be installed, and EPA 608.
See HVAC contractors coverage → -
Lawn care and landscaping insurance
Thrown rocks, chemical drift, trucks and trailers, mowers and equipment, and Tennessee’s pest control charter.
See lawn care and landscaping coverage → -
Another trade?
Roofing, remodeling, painting, handyman work or something else? Tell us about your work and we’ll talk through what may be available.
Tell us about your work →
Workers’ comp in Tennessee
Do I need workers’ comp in Tennessee?
Sources: Tennessee Bureau of Workers’ Compensation: Construction · Tennessee Bureau of Workers’ Compensation: Exemptions and Exemption Registry
- Construction businesses: one employee or moreTennessee construction employers with one or more employees must carry workers’ comp, including part-time, seasonal and family workers. Office staff count too.
- Other businesses: five employees or moreBusinesses outside construction generally need workers’ comp once they have five or more employees.
- Owners can apply for an exemptionOwners of construction businesses must cover themselves unless they qualify for and register an exemption with the state’s Workers’ Compensation Exemption Registry. Exemptions last two years and only cover the owner, never the employees.
- A 1099 doesn’t settle itThe state looks at how the work is controlled, not just how someone is paid. A worker you pay on a 1099 may still count as an employee.
Licensing, insurance and bonds
Licensing and proof of insurance in Tennessee
In Tennessee, projects of $25,000 or more generally need a contractor’s license from the Board for Licensing Contractors, and the Board asks for proof of general liability and workers’ comp. Smaller jobs may need a limited license, a Home Improvement license or a local license, depending on the trade and where you work.
-
$25,000 and up
Projects of $25,000 or more generally require a Tennessee contractor’s license with the right classification for your trade.
Source: Tennessee Board for Licensing Contractors: Contractor license · Tennessee Contractor Classification Outline
-
Proof of insurance
When you apply for or renew a contractor’s license, the Board asks for a certificate of insurance for general liability, with the Board listed as certificate holder, and proof of workers’ comp or an exemption.
Source: Tennessee Board for Licensing Contractors: Insurance Resource Information for Licensees
-
Home Improvement license
Davidson and Rutherford are among the counties that require a Home Improvement license for residential remodeling projects from $3,000 to under $25,000, with a $10,000 bond or letter of credit requirement.
Source: Tennessee Board for Licensing Contractors: Home Improvement Contractor
We’re an insurance agency, not a licensing office. Rules change, and cities and counties can add their own, so always confirm current requirements with the Board for Licensing Contractors and your local codes office.
Certificates of insurance
Need a certificate of insurance for a job?
General contractors, property managers, HOAs and permit offices often want a certificate of insurance before you start. Call us at 615-562-5100 with the certificate holder’s name and address and what they’re asking for. When your policy is in place and your request comes in during office hours, we’ll work to get your certificate to you as quickly as we can.
A certificate only shows the coverage your policy already has. It can’t add coverage or change your policy. Additional insured, waiver of subrogation and primary and noncontributory requests depend on your policy’s terms, so send those to us early and we’ll tell you what’s possible.
What to have ready when you call
- The certificate holder: Their full legal name and mailing address.
- The job: The project name or address, if they want it listed.
- Their requirements: The insurance page of the contract, or the list of limits and endorsements they asked for.
Areas we serve
Where do we work with contractors?
Our only office is in Mt. Juliet, and we work with contractors across Wilson, Rutherford and Davidson counties, including Lebanon, Watertown, Murfreesboro, Smyrna, La Vergne, Hermitage, Old Hickory and Nashville, plus Gallatin, Hendersonville and all of Middle Tennessee.
- Wilson CountyMt. Juliet, Lebanon and WatertownHome of our office on Providence Pkwy.
- Davidson CountyHermitage, Old Hickory, Donelson and NashvilleWest on I-40 and Lebanon Rd.
- Rutherford CountyMurfreesboro, Smyrna and La VergneSouth on I-840 and I-24.
- Sumner CountyGallatin and HendersonvilleNorth across Old Hickory Lake.
- All of Middle TennesseeMiddle TennesseeAnywhere in Middle Tennessee. Most of what you need can be handled by phone and email, and you’re always welcome at the office.
Our office sits on Providence Pkwy, just off I-40 in Mt. Juliet. A lot of our neighbors in the trades spend the day on I-40 and Lebanon Rd heading toward Hermitage, Donelson and Nashville, or on I-840 and I-24 down to Murfreesboro, Smyrna and La Vergne. Wherever the work takes you, you can call one local office for your business coverage. One local detail worth knowing: Davidson and Rutherford are on the state’s list of counties that require a Home Improvement license for remodeling projects from $3,000 to under $25,000, and that license comes with a $10,000 bond or letter of credit requirement.
Getting started
How does getting a quote work?
Call or request a quote
Call 615-562-5100 or use the form below. Tell us what kind of work you do and who you work for.
We talk it through
We’ll ask about your crew, vehicles, equipment, contracts and any licensing or permit requirements, and explain your options in plain language.
You decide
We’ll go over the coverage options available to you, what each one does and what it costs, so you can choose what fits. No pressure.
Your agent
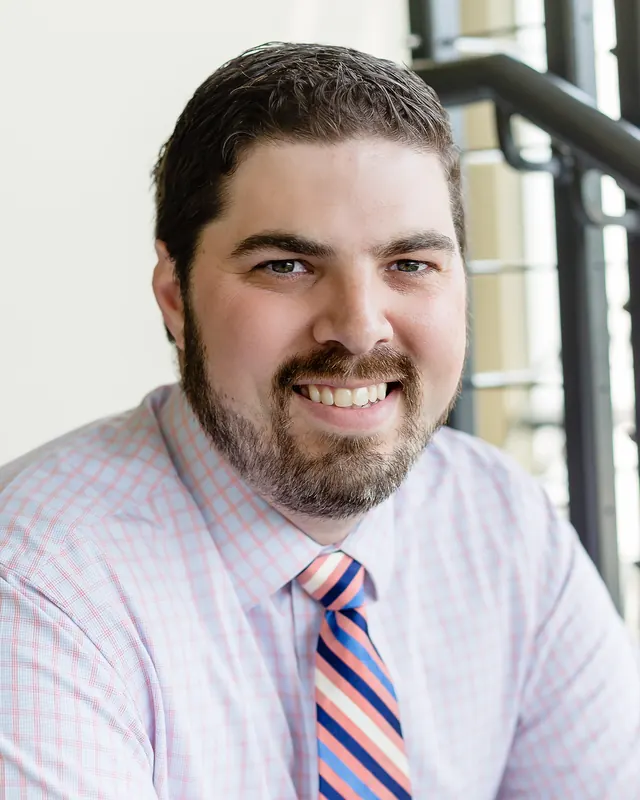
Meet Dustin Rodgers
I’m Dustin Rodgers, and I run Rodgers Insurance Agency from our office on Providence Pkwy in Mt. Juliet. I grew up in Middle Tennessee, and a lot of the people I work with are small business owners who build, fix and maintain this area for a living. I’ve been in the insurance business since March 2011.
When you call, you’ll talk with me or someone on my team who knows your file. We’ll listen to how your business actually runs, explain things in plain language, and be here when you need a certificate, a policy change or help with a claim.
- In the insurance business since March 2011
- Trevecca Nazarene University
- Hume Fogg Academic High School
FAQ
Frequently Asked Questions
Updated
What insurance does a contractor need in Tennessee?
Most contractors look at general liability, workers’ compensation, commercial auto, and tools and equipment coverage, plus any bonds a license, permit or contract calls for. Tennessee construction employers with even one employee generally must carry workers’ comp. The right mix depends on your trade, your crew and your contracts, so let’s talk it through.
Do contractors in Tennessee need workers’ compensation insurance?
Generally, yes, if you have even one employee. Tennessee construction employers with one or more employees must carry workers’ comp, including for part-time and family workers. Most businesses outside construction need it at five or more employees. Eligible owners can apply to exempt themselves through the state’s exemption registry, but employees still have to be covered.
What’s the difference between general liability and workers’ comp?
General liability can help with claims that your work hurt someone else or damaged their property, like a customer or a neighbor. Workers’ comp can help pay medical bills and part of lost wages when your own employee is hurt on the job. Most contractors with a crew look at both. Limits, exclusions and terms vary by policy.
Are my tools and equipment covered by general liability?
No. General liability is for claims from other people. Tools and equipment that travel with you are usually insured under an inland marine or contractor’s equipment policy, which can help with covered theft or damage. Coverage for gear left in an unattended vehicle may have conditions, so we’ll go over the details with you.
Does my personal auto policy cover my work truck?
Often, no. Personal auto policies commonly limit or exclude vehicles used mainly for business, especially trucks, vans and trailers that carry tools, materials and employees. A commercial auto policy is built for that. Tell us how you use each vehicle and who drives it, and we’ll help you sort out what fits.
Is a contractor bond the same as insurance?
No. A bond protects the party who asked for it, like a licensing board, a city or a project owner, by guaranteeing you’ll follow the rules or finish the work. If the surety pays a valid claim, you’re generally expected to pay it back. We can help you look at license, permit and contract bond options.
Do I need pollution coverage?
It depends on your work. Many general liability policies limit or exclude pollution claims, which can matter for sewer and drain work, refrigerants, mold or spraying chemicals. Contractors pollution liability may be available, depending on carrier eligibility and underwriting. Tell us what you do and we’ll go over your options.
How fast can I get a certificate of insurance?
Call 615-562-5100 with the certificate holder’s details. When your policy is in place and the request comes in during office hours, we’ll work to get it to you as quickly as we can. A certificate can only show coverage your policy already has, and additional insured requests depend on your policy’s terms.
Do you work with trades that aren’t listed here?
We’re glad to talk with other trades too. Which coverages are available depends on your work, carrier eligibility and underwriting, so call 615-562-5100 or choose Other trade on the form below and tell us what you do. We’ll be straight with you about what we can help with.
Do you only work with contractors in Mt. Juliet?
No. Our office is on Providence Pkwy in Mt. Juliet, but we work with contractors across Wilson, Rutherford and Davidson counties, including Lebanon, Murfreesboro, Smyrna, La Vergne, Hermitage and Nashville, plus Gallatin, Hendersonville and the rest of Middle Tennessee.
Request a business insurance quote
Tell us a little about your business, and we’ll call you back during business hours. Prefer to talk now? Call 615-562-5100.
It helps to have your business name and structure, your trade and license number, yearly revenue and payroll, how many employees and vehicles you have, and your current policies if you have them.
Stop By or Call Our Mt. Juliet Office
Have a job starting soon, a contract that asks for certain coverage, or just a question? Give us a call, or set a time to sit down with Dustin in person or by phone.
- Address
- 1982 Providence Pkwy Ste 257
Mt Juliet, TN 37122 - Directions
- Providence area, second floor, same building as Oscar’s Taco Shop
- Phone
- 615-562-5100
- Reviews
- Google reviews · Leave a review
- Hours
- Monday–Friday, 8:00 AM–5:00 PM
Saturday–Sunday, closed